August 2026 MBS Housing Playbook: Treasury Leans on Long Rates, CPI Tests the Floor
The Treasury Department just became part of the rate desk.
The U.S. joined Japan in supporting the yen, highlighted a liquidity path that could help foreign central banks raise dollars without selling Treasuries, and changed future auction guidance from possible "increases" to possible "changes." Traders read the package as an effort to keep long yields from breaking higher.
Then payrolls fell by 23,000, prior months were revised down by 103,000, and the 10-year yield eased to roughly 4.64%.
That is a real rally setup. It is not yet a float signal.
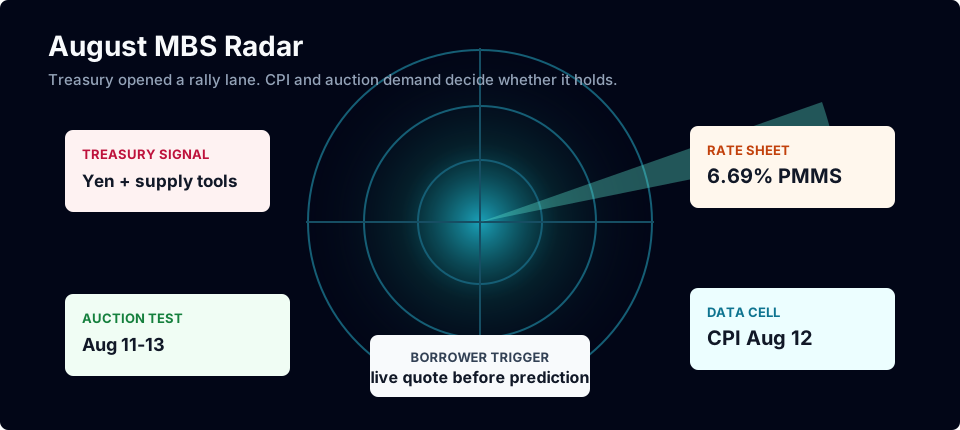
Freddie Mac's Thursday benchmark still rose to 6.69%, Treasury did not actually reduce August long-bond auction sizes, and CPI lands beside the 10- and 30-year auctions. Live MBS pricing and the borrower's actual quote must prove that policy intent reached the rate sheet.
Do not sell a forecast. Run a controlled experiment with a lock trigger.
August 9 desk call
Treasury opened a rally lane. CPI and auction demand decide whether MBS can drive through it.
Bias hold with lock sensitivity until same-day Treasuries, MBS, and the borrower quote confirm broad improvement. Float only with a written ceiling and room for a hot-data reversal.
Revised five-business-day setup
| Path | Desk weight | Confirmation | Default action |
|---|---|---|---|
| Choppy relief, no clean pass-through | 45% | Treasuries hold below the recent highs, but MBS or lender pricing lags | Hold or lock-sensitive; reprice, do not predict. |
| Bond rally broadens into mortgages | 30% | Cooler CPI, solid 10- and 30-year auctions, lower yields, firmer MBS, and better borrower quotes | Float only when the worse payment works and a written lock trigger remains intact. |
| Policy signal is overwhelmed | 25% | Hot CPI, weak auction demand, oil shock, wider mortgage spread, or a Treasury reversal | Lock exposed files and protect qualification-sensitive borrowers. |
The policy move lowers the probability of an uncontrolled long-end breakout. It does not justify an automatic rate cut in the forecast because the announced August auction sizes are unchanged and the same intervention can be read as evidence of market fragility.
MBS Rate Desk Refresh
Pipeline note August 29, 2026
Rate desk read: inventory gives agents room to negotiate structure, but borrower margin still decides whether the deal survives.
Snapshot as of Aug 29, 2026, 1:21 PM EDT from live BlueSkyFI rate, housing, labor, and consumer data.
Desk translation
- Rate desk: Rate sheet first: the daily 30-year conforming index is 6.7%, -0.0% versus roughly a week ago. Freddie's weekly 30-year benchmark is 6.7%, the 10-year Treasury is 4.7%, and the mortgage-to-Treasury gap is about 2.0 pp.
- Inventory desk: Agent angle: existing-home supply is 4.6 months, existing inventory is about 1.54M, and inventory is -1.9% month over month. The housing-market label is Competitive.
- Borrower margin: Borrower margin check: the saving rate is 3.0%, real wage growth versus inflation is -0.4%, unemployment is 4.1%, and weekly claims are around 203K.
- Client move: Default client move: compare price cuts, closing-cost credits, and buydowns before advising a seller to simply lower the list price.
Use this as the morning rate-desk note: one clean read, one exposed payment, one trigger, and one next call. The sections below turn the live rate, spread, inventory, labor, and margin read into loan-originator talking points.
The August LO signal board
| Desk | Evidence order | Client translation | Tool |
|---|---|---|---|
| Live pricing | Current rate sheet, MBS coupon, 10-year Treasury, spread | "Here is what moved today and what did not." | Treasury Spread |
| Five-day call | Direction probabilities, expected basis-point move, hard-data alignment | "The forecast is a risk range, not a promise." | Rate Lock Risk |
| Event risk | CPI and 10-year auction Aug 12; PPI and 30-year auction Aug 13 | "Inflation and Treasury demand land inside your decision window." | Lock vs. Float |
| Treasury policy | Yen intervention, foreign-dollar liquidity, issuance language, buybacks | "Policy can cap the tail, but your quote must confirm the benefit." | Treasury Spread |
| Borrower margin | Payment, DTI, reserves, cash to close, lock expiry | "We float only while the worse payment still works." | Mortgage Payment |
| Housing structure | Inventory, concessions, price, repairs, buydown | "We solve the bottleneck, not decorate the offer." | Seller Strategy |
| Refi | Note rate, costs, savings, break-even, time in home | "A lower quote must survive the full timeline." | Refinance Break-Even |
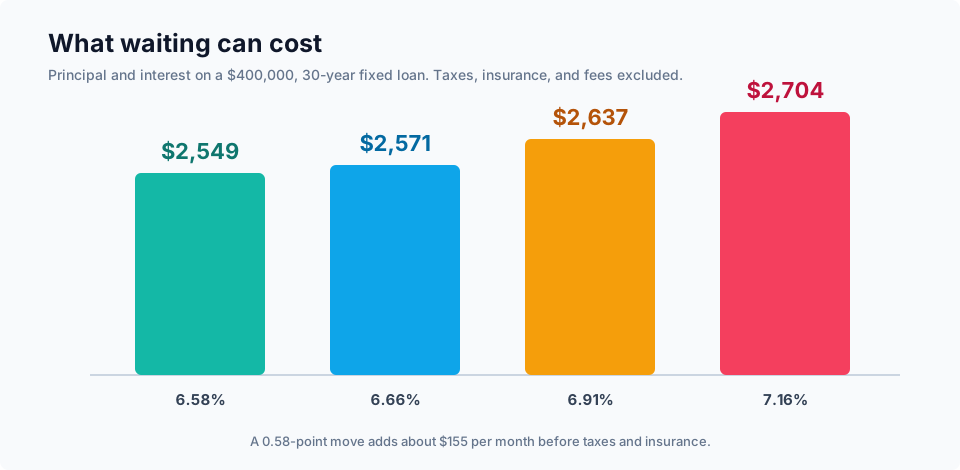
Chart: the cost of rate drift
August lock and float rules
Lock pressure
Lock pressure strengthens when live mortgage pricing, the 10-year Treasury, and MBS movement agree; the mortgage spread is not improving; the event lands before the borrower has room to recover; and the worse payment threatens qualification or comfort.
Desk line: "The market and your payment are pointing the same way. We protect the transaction."
Float pressure
Float pressure strengthens only when mortgage rates and Treasuries are improving together, the spread confirms rather than steals the move, the 10- and 30-year auctions clear cleanly, and the borrower can absorb a CPI reversal.
Desk line: "The relief is broad enough to watch, and your fallback payment still works."
Hold
Hold is an active position when data conflicts. It means rerun the quote, preserve optionality, and define the next check. It does not mean ignore the borrower until Friday.
Desk line: "We do not have enough edge to gamble. Here is the number that changes the call."
How Gemini and expert calls fit
BlueSkyFI's daily five-business-day prediction now has to produce a hard-data read before it can influence the recommendation. It uses mortgage-rate direction, Treasuries, mortgage spreads, bond proxies, event risk, and fresh market headlines.
Gemini can then check up to three fresh, public rate-desk or industry reads. A dated public Barry Habib or MBS Highway stance can be included. An annual outlook, marketing page, old video, or subscriber-only note cannot be converted into today's lock/float call.
Expert agreement is recorded. It does not earn a free vote. Expert disagreement reduces AI influence, while hard data remains the control.
That gives the desk a useful audit:
- baseline recommendation without Gemini,
- Gemini probability recommendation,
- hard-data verdict,
- fresh public expert consensus,
- final guarded recommendation,
- five-business-day outcome.
Read the full method in How BlueSkyFI MBS manages rate desk signals and the track-record reset explainer.
Client scripts
Buyer
"The weekly benchmark is 6.69%, but Friday's bond rally came after that survey. I am showing today's live quote, a quarter-point worse case, and the payment ceiling. If the ceiling breaks, we lock, lower the target, or restructure."
Lock or float
"Treasury is trying to keep long rates from breaking higher, but CPI and this week's bond auctions can still reverse pricing. We float only while the worse payment works and the written lock trigger has not fired."
Agent and seller
"Inventory gives us more structure, but the median price and financing cost still squeeze the buyer. Let us compare the seller credit, price cut, buydown, and repair option against the buyer's real bottleneck."
Refi
"A cooler inflation headline is not a refinance. We act when the quote creates enough monthly savings to repay costs inside the time you expect to keep the loan."
August desk calendar
- August 11: $58 billion 3-year Treasury auction.
- August 12: July CPI and real earnings.
- August 12: $42 billion 10-year Treasury auction.
- August 13: July PPI and $25 billion 30-year Treasury auction.
- August 18: import and export prices.
- August 26: July PCE and the second estimate of second-quarter GDP.
- August 28: preliminary payroll benchmark revision.
- Every Thursday: Freddie Mac PMMS and weekly claims.
- Every pricing day: live MBS, Treasury, spread, and rate-sheet check.
Bottom line
August is not a float month or a lock month.
It is a prove it month.
Prove Treasury's support is more than a signal. Prove inflation cooling is durable. Prove auction demand and MBS are passing it through. Prove the borrower's payment can survive the wrong move.
Then make the call.
Sources
- Federal Reserve FOMC statement, July 29, 2026: federalreserve.gov/newsevents/pressreleases/monetary20260729a.htm
- Federal Reserve 2026 FOMC calendar: federalreserve.gov/monetarypolicy/fomccalendars.htm
- Freddie Mac PMMS, August 6, 2026: freddiemac.com/pmms
- BLS Consumer Price Index, June 2026: bls.gov June CPI
- BEA Personal Income and Outlays, June 2026: bea.gov June income and PCE
- BLS Producer Price Index, June 2026: bls.gov June PPI
- BLS Employment Situation, June 2026: bls.gov June jobs
- NAR Existing-Home Sales, June 2026: nar.realtor June report
- Census New Residential Construction, June 2026: census.gov June construction
- BLS August 2026 release calendar: bls.gov August calendar
- BEA release schedule: bea.gov release schedule
- U.S. Treasury quarterly refunding statement, August 5, 2026: home.treasury.gov/news/press-releases/sb0590
- Treasury Borrowing Advisory Committee report, August 5, 2026: home.treasury.gov/news/press-releases/sb0591
- BLS Employment Situation, July 2026: bls.gov July jobs
- AP on the August 6 Freddie Mac mortgage benchmark: apnews.com
- Bloomberg reporting republished by Yahoo Finance, August 9, 2026: finance.yahoo.com